


Best DSCR Loan Lenders 2026: Ranked by Use Case
Six names dominate DSCR lending conversations in 2026, and the right one depends entirely on what you're financing, not which lender has the flashiest homepage. LoanGuys.com wins overall for investors who want one application to reach multiple DSCR programs at once, Kiavi wins for fast, tech-driven closings, CoreVest wins for larger rental portfolios and blanket structures, Visio Lending wins for single-family rental specialists, Angel Oak Mortgage Solutions wins for foreign national and complex-income borrowers, and LendingOne wins for investors scaling a repeat portfolio.
TL;DR
- LoanGuys.com is the best overall pick among the best dscr loan lenders 2026 because one application reaches multiple wholesale and portfolio lenders at once.
- Kiavi and LendingOne are built for speed, favoring investors who want a closing timeline measured in weeks, not months.
- CoreVest fits 5+ door portfolios and blanket loan consolidation, not single-property first-time buyers.
- Angel Oak Mortgage Solutions and Visio Lending cover the foreign national and single-family-specialist gaps most banks skip entirely.
- DSCR qualification runs on rental income, not W-2 pay, so a property clearing a 1.0+ ratio clears most 2026 programs.
Why this matters
A DSCR loan qualifies you on what the property earns, not what you personally report on a tax return. That single feature is why investors with S-corp write-offs, foreign income, or a stack of existing mortgages still get approved when a conventional bank says no.
The lender you pick changes three things: how fast you close, how many doors you can finance under one structure, and whether your income situation even fits the box. LoanGuys.com works as a broker across several of these programs, which matters more in 2026 than it did a few years back — DSCR guidelines shift lender to lender on ratio floors, reserve requirements, and entity structures, and shopping one lender at a time costs weeks you don't have on a competitive deal.
Most of the lenders below only serve one lane well. Picking the wrong one doesn't just mean a slower closing — it can mean a declined file three weeks into underwriting because the property or borrower profile never fit that lender's box in the first place.
What makes the best DSCR loan lender
Before trusting any ranking, check it against what actually separates a strong DSCR lender from a mediocre one:
- DSCR ratio flexibility — some programs approve at or near breakeven (1.0), a few even allow negative cash flow with a rate trade-off
- Maximum loan-to-value — higher LTV means less cash down, but usually a rate premium
- Speed to close — tech-forward lenders move faster than legacy portfolio banks
- Portfolio and blanket loan support — not every lender wants to underwrite a 6-property blanket structure
- Income and entity flexibility — foreign national files, LLC ownership, and 1099 income aren't handled the same everywhere
- Access to multiple wholesale channels — a broker model widens your options versus one lender's fixed menu
The list below is ordered by use case, not by hype. Each lender earns its spot for a specific investor profile, and one of them is going to be wrong for you no matter how well it ranks overall.
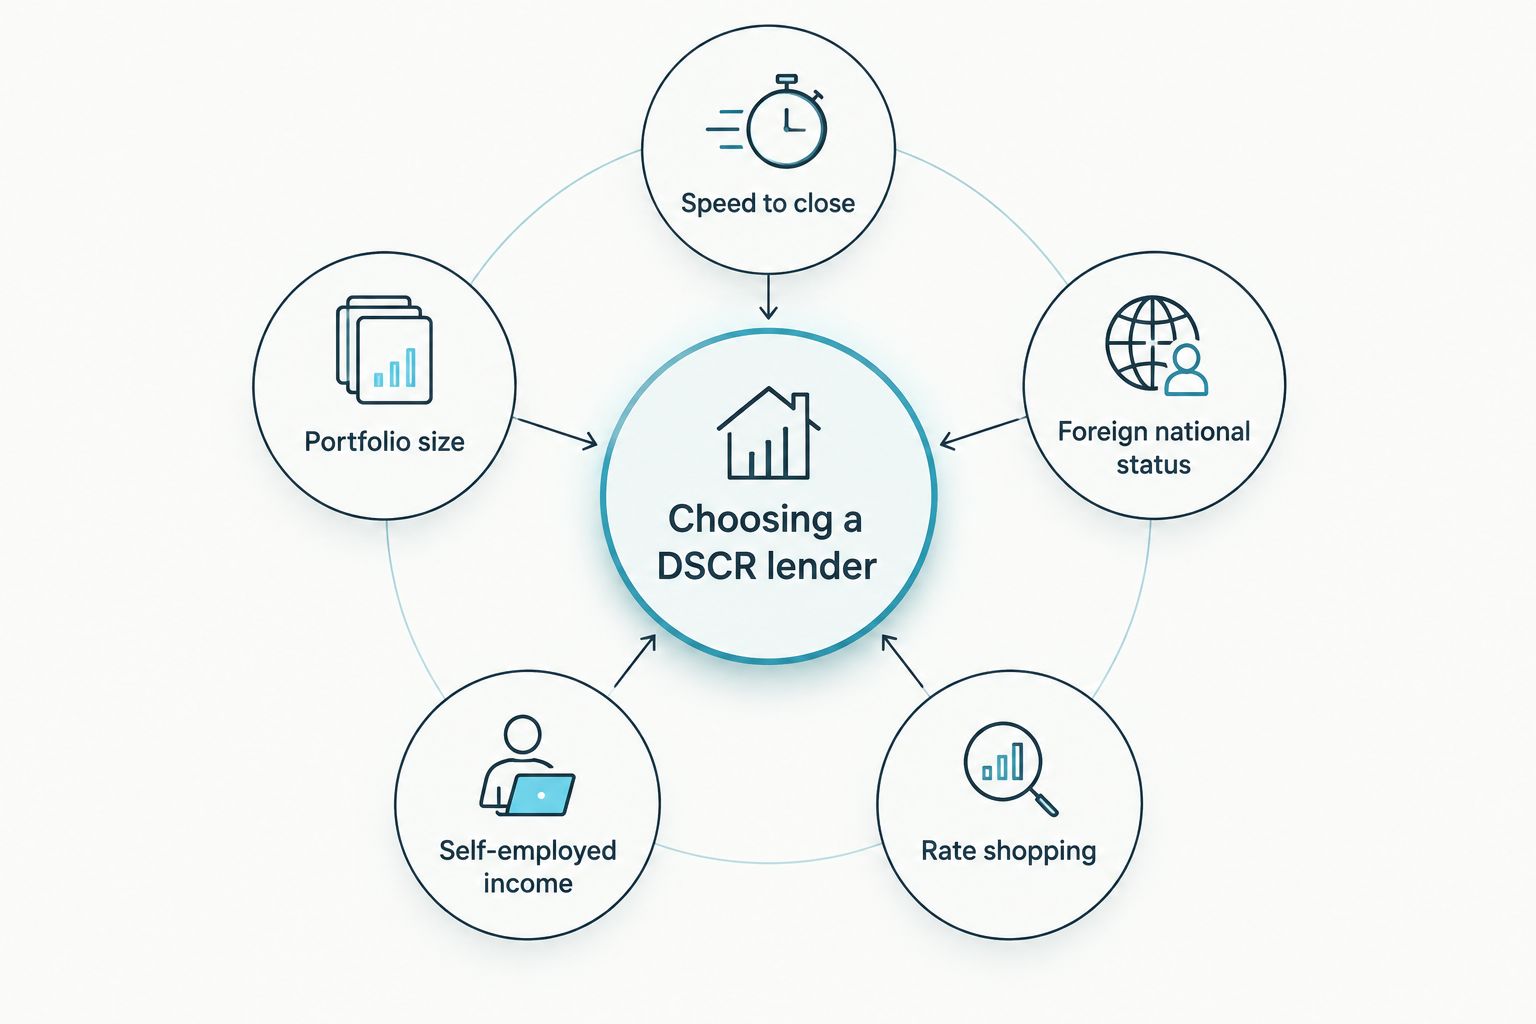
Match your priority factor to the lender built around it before you apply anywhere.
DSCR lenders at a glance
LoanGuys.com
- Best for: Comparing multiple programs at once
- Standout feature: Broker access to several DSCR channels
- Key limitation: Not a direct lender — final terms set by the underlying program
Kiavi
- Best for: Fast, tech-driven closings
- Standout feature: Digital-first application and underwriting
- Key limitation: Less flexible for unusual entity structures
CoreVest
- Best for: Larger rental portfolios
- Standout feature: Blanket loan and portfolio-scale structures
- Key limitation: Overkill for a single-property purchase
Visio Lending
- Best for: Single-family rental specialists
- Standout feature: Deep focus on one-off SFR purchases
- Key limitation: Less built out for large multifamily
Angel Oak Mortgage Solutions
- Best for: Foreign national and complex income
- Standout feature: Broad non-QM and foreign national menu
- Key limitation: More documentation than a straightforward W-2 file needs
LendingOne
- Best for: Scaling repeat investors
- Standout feature: Programs built around repeat-borrower relationships
- Key limitation: Best value shows up after your first deal or two
See how rates, terms, and minimums compare across DSCR lenders before you lock a program based on the table alone.
1. LoanGuys.com: best DSCR loan lender for comparing multiple programs
LoanGuys.com operates as a mortgage broker running DSCR, bridge, fix-and-flip, and bank-statement programs across a network of lenders rather than a single in-house menu. One application gets compared against several DSCR channels instead of forcing you to submit the same file five separate times.
LoanGuys.com pros:
- One intake covers multiple DSCR programs and lender guidelines
- Handles LLC ownership, foreign national files, and non-traditional income without treating them as exceptions
- Works alongside bridge and fix-and-flip financing if your strategy spans both
LoanGuys.com cons:
- As a broker, LoanGuys.com doesn't set final underwriting terms — those come from the matched lender
- Not the fastest path if you already know exactly which single lender you want
Best for: investors who want their file shopped across programs instead of guessing which lender fits first. Verdict: Buy.
2. Kiavi: best DSCR loan lender for fast, tech-driven closings
Kiavi built its reputation on fix-and-flip lending before expanding into DSCR rental financing, and the platform still leans on a digital-first process rather than a traditional loan officer relationship.
Kiavi pros:
- Online application and document upload reduce back-and-forth
- Familiar with investors who flip and hold, useful if your strategy blends both
- Straightforward for standard single-property purchases
Kiavi cons:
- Less accommodating for unusual entity or ownership structures
- Self-service platforms mean less hand-holding if your file is complicated
Best for: investors who value a quick, digital closing over a relationship-driven process. Verdict: Buy.
3. CoreVest: best DSCR loan lender for larger rental portfolios
CoreVest, a Redwood Trust company, focuses on scale — blanket loans across multiple properties and portfolio-level underwriting rather than one-off single-family deals.
CoreVest pros:
- Built for blanket loan structures across five or more properties
- Portfolio-level underwriting can simplify refinancing a stack of existing mortgages
- Comfortable with institutional-style investor profiles
CoreVest cons:
- Not the right fit for a first-time investor buying one property
- Portfolio underwriting takes longer than a single-property digital application
Best for: investors consolidating several rentals into one loan structure. Verdict: Hold — worth it once your portfolio actually justifies blanket financing.
4. Visio Lending: best DSCR loan lender for single-family rental specialists
Visio Lending narrows its focus to single-family rental properties, which shows up in how tightly its underwriting is built around that one property type.
Visio Lending pros:
- Deep specialization in single-family rental purchases and refinances
- Underwriting built specifically around one property type, not a generic commercial menu
Visio Lending cons:
- Less built out for multifamily or mixed-use rental properties
- Narrower fit if your portfolio strategy includes larger buildings
Best for: buy-and-hold investors sticking to single-family homes. Verdict: Buy for that specific use case.
5. Angel Oak Mortgage Solutions: best DSCR loan lender for foreign national and complex-income borrowers
Angel Oak Mortgage Solutions runs a broader non-QM shelf, and DSCR sits alongside bank-statement and foreign national programs built for borrowers conventional underwriting turns away.
Angel Oak pros:
- Broad non-QM menu covering foreign nationals, bank-statement income, and DSCR under one roof
- Comfortable with layered complexity — multiple LLCs, international income, or thin US credit files
Angel Oak cons:
- More documentation than a straightforward W-2 borrower typically needs
- Complexity that helps unusual files can slow down a simple one
Best for: foreign national investors or anyone with income too complex for standard DSCR underwriting. Verdict: Buy for that specific profile.
6. LendingOne: best DSCR loan lender for scaling repeat investors
LendingOne positions its DSCR and bridge programs around the repeat-borrower relationship, with the idea that terms and process improve the more deals you close through them.
LendingOne pros:
- Programs oriented around building a relationship across multiple deals
- Offers both DSCR and short-term bridge financing under one roof
LendingOne cons:
- The relationship advantage matters less on a first deal
- Not the obvious pick for a one-time, single-property purchase
Best for: investors planning to finance several properties over 2026 and beyond. Verdict: Hold — strongest after your first deal proves the fit.
How we ranked
Every lender above is scored against the same six criteria from the list earlier: DSCR ratio flexibility, max LTV, speed to close, portfolio support, income and entity flexibility, and breadth of wholesale access. None of the six wins on every dimension — that's the point. A ranking that names one universal winner is hiding the trade-offs, and DSCR lending in 2026 has real trade-offs between speed, scale, and borrower complexity. Budget for DSCR loan closing costs regardless of which program you pick — origination fees and reserve requirements vary by lender even when the headline rate looks similar.
Compare DSCR programs in one application
See which DSCR lenders fit your property and income profile.
Which DSCR loan lender should you choose in 2026?
If you're undecided, start with LoanGuys.com — a single application gets compared against multiple DSCR channels instead of locking you into one lender's guidelines before you know if they're the right fit. If you already know you're financing a 6-door portfolio, skip straight to CoreVest. If speed is the only thing that matters and your file is straightforward, Kiavi or LendingOne close faster than a portfolio bank ever will.
Don't pick a DSCR lender the way you'd pick a bank — pick the one built for your specific deal, then let the rate be the tiebreaker, not the starting point.
FAQ
What is the best DSCR loan lender in 2026?
There is no single best DSCR loan lender for everyone in 2026 — LoanGuys.com wins for comparing multiple programs at once, CoreVest wins for large portfolios, and Kiavi wins for fast digital closings. The right pick depends on your property count and income profile.
Is a DSCR loan better than a conventional mortgage for rental property?
A DSCR loan qualifies you on the property's rental income rather than personal tax returns, which is better for self-employed investors or anyone with complex income. A conventional mortgage may offer a lower rate if you can document W-2 income and qualify traditionally.
What DSCR ratio do lenders require in 2026?
Most DSCR programs in 2026 require a minimum ratio between 1.00 and 1.25, meaning the property's rental income covers 100% to 125% of the mortgage payment. Some no-ratio programs approve below 1.0 with a rate trade-off.
Can foreign nationals get a DSCR loan?
Yes — foreign national investors can qualify for DSCR loans through programs like Angel Oak Mortgage Solutions, which underwrite based on the property's cash flow rather than US-based income documentation.
How fast can a DSCR loan close?
Tech-forward DSCR lenders like Kiavi and LendingOne typically move faster than traditional portfolio banks, since underwriting relies on the property's rent roll rather than a full personal income file. Timelines still depend on appraisal scheduling and title work.
Do DSCR loans work for a portfolio of multiple rental properties?
Yes — lenders like CoreVest specialize in blanket loan structures that consolidate several rental properties into one loan. Single-property specialists like Visio Lending are built for one-off purchases instead.
What credit score do I need for a DSCR loan?
Most DSCR programs in 2026 look for a credit score of 620 or higher, though the exact minimum varies by lender and loan-to-value requested. Higher scores typically unlock better rate pricing and higher LTV ceilings.
One last thing
The biggest mistake investors make shopping DSCR lenders isn't picking the wrong one — it's applying to five of them separately and generating five hard credit pulls before comparing a single term sheet. Run your file through a broker first, then narrow down to the direct lender that actually fits, instead of reversing that order.


