


DSCR Loan for Newly Formed LLC: 2026 Closing Guide
A DSCR loan for a newly formed LLC closes the same way one for a five-year-old holding company does: lenders check the property's cash flow and the entity's paperwork, not how long the LLC has existed. Most DSCR lenders in 2026 apply zero seasoning requirement to the borrowing LLC, but they do want five specific documents in hand before they'll issue a closing disclosure — miss one and the file stalls at underwriting, not at approval.
TL;DR
- A DSCR loan for a newly formed LLC can close with zero seasoning required at most lenders in 2026.
- Underwriters ask for five core LLC documents instead of months of business history.
- DSCR ratio requirements, typically 1.0 to 1.25, apply the same to a day-old LLC and a ten-year-old one.
- Personal guarantees are still standard even when the entity itself has no track record.
- LoanGuys closes DSCR loans for LLC-owned rental properties without an entity-age cutoff.
Why this matters
Investors form a new LLC per property, per portfolio, or per state almost every closing season, then hit a wall when a loan officer asks how long the entity has existed. That question matters for a conventional business loan. It barely matters for DSCR loans for LLC-owned rental properties, because the loan qualifies off the subject property's rent, not the LLC's balance sheet or tax filings.
The practical risk isn't entity age — it's missing paperwork. A same-week LLC formation with all five documents in order closes faster than a two-year-old LLC missing its operating agreement.
Can you close a DSCR loan with a newly formed LLC in 2026?
Yes. The table below shows what changes — and what doesn't — between a brand-new entity and one that's been filing for a year or more.
Seasoning period
- New LLC (0-90 days old): None at most DSCR lenders
- Established LLC (12+ months): None
Articles of Organization
- New LLC (0-90 days old): Required
- Established LLC (12+ months): Required
EIN letter from the IRS
- New LLC (0-90 days old): Required
- Established LLC (12+ months): Required
Signed operating agreement
- New LLC (0-90 days old): Required, often executed right before closing
- Established LLC (12+ months): Required
Business bank account
- New LLC (0-90 days old): Not required to qualify
- Established LLC (12+ months): Sometimes used to show reserves
Personal guarantee from 20%+ owners
- New LLC (0-90 days old): Standard
- Established LLC (12+ months): Standard
The only real gap for a brand-new LLC is timing: the operating agreement and resolution to borrow need to exist and be signed before the closing package goes out, which means the entity has to be set up with intent to close, not scrambled together the week of closing.
The 5 documents your new LLC needs before closing
- Articles of Organization (or Certificate of Formation) — proves the LLC is legally registered with the state.
- EIN letter (CP 575) from the IRS — confirms the LLC has its own tax ID, separate from the members' Social Security numbers.
- Signed operating agreement — spells out ownership percentages and who has authority to sign for the LLC.
- Resolution/authorization to borrow — a one-page document, signed by all members, authorizing the specific loan.
- Government-issued ID for each member owning 20% or more — needed for the personal guarantee.
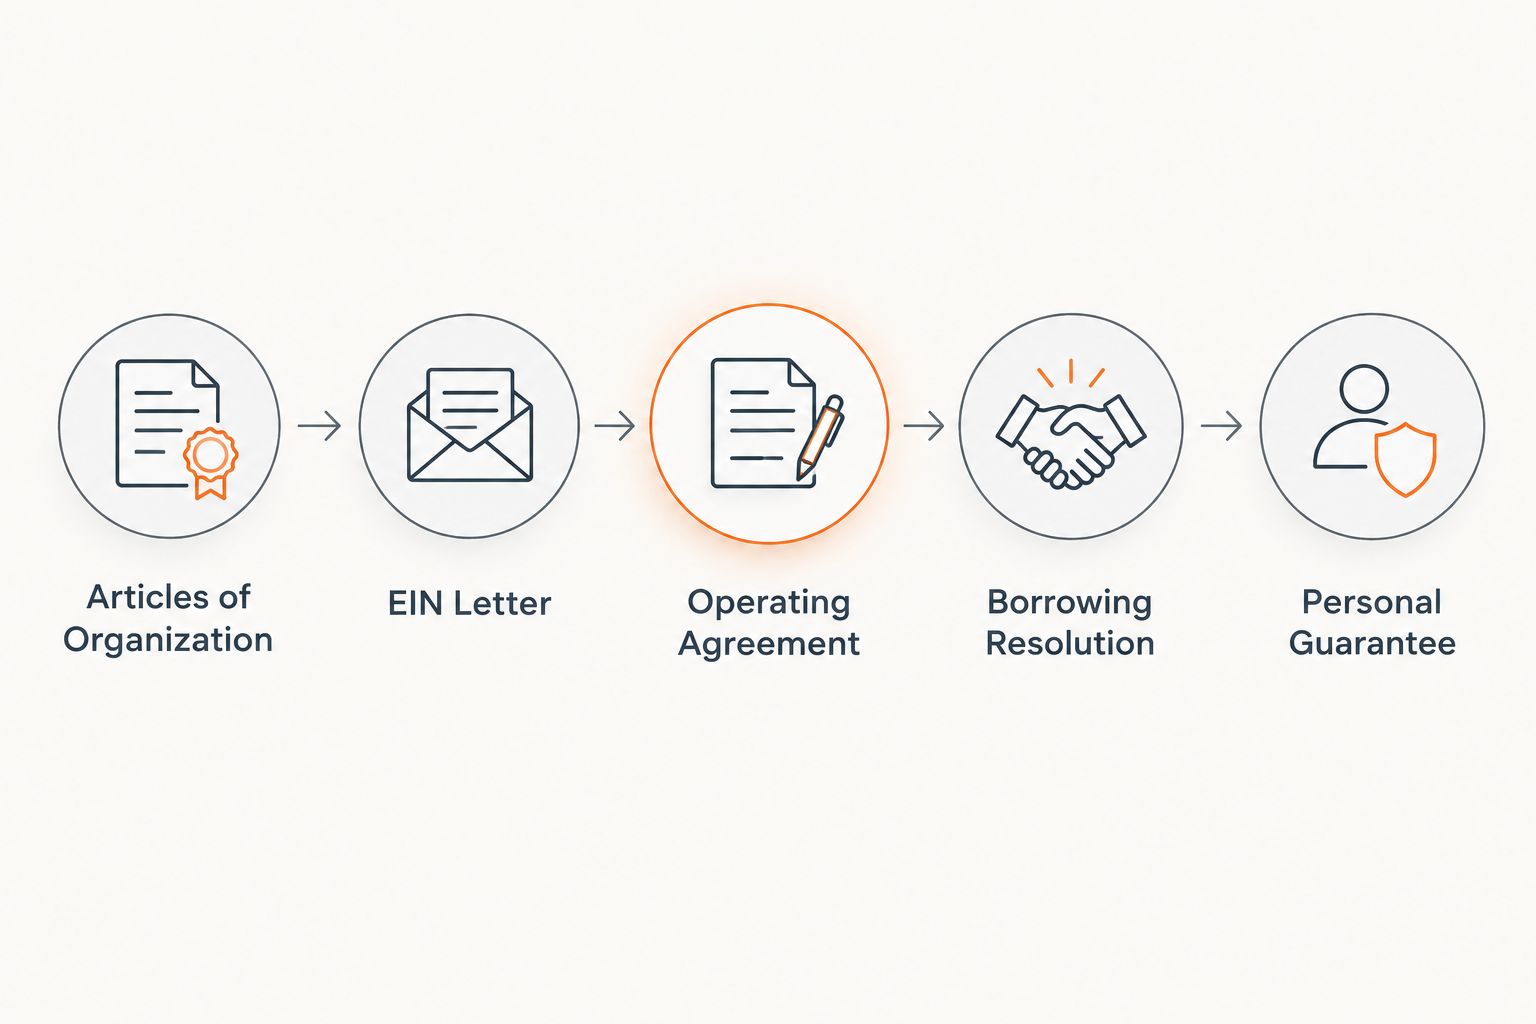
Each document proves the LLC can legally borrow and repay in its own name.
Get these five in order before you start shopping for a property, and the LLC's age stops being a conversation at all.
Why LLC age doesn't matter to DSCR underwriting
- The loan qualifies off the property, not the entity. DSCR underwriting divides gross rental income by the mortgage payment (principal, interest, taxes, insurance, and association dues) — a ratio that's identical whether the LLC filed last week or in 2019.
- The personal guarantee shifts the risk. Every member with 20% or more ownership signs personally, so the lender isn't relying on the LLC's credit history because there usually isn't one to rely on.
- Title and vesting protect the lender regardless of entity age. The property secures the loan; the LLC just holds title.
- State good-standing status matters more than founding date. A lender checks that the LLC is active and compliant with its state of formation, not how long it's been active.
- DSCR ratio thresholds don't shift for new entities. Most lenders still require a ratio between 1.0 and 1.25, meaning the property needs to at least cover its own payment.
- Multi-member LLCs need every 20%+ owner's signature, whether the LLC is one week or ten years old — this is an ownership-structure rule, not an age rule.
Does the LLC need its own credit history to qualify?
No — a newly formed LLC has no credit history, and DSCR lenders don't require one. Underwriting relies on the personal guarantee and credit of the members owning 20% or more, plus the DSCR ratio the property produces, not a business credit score the entity hasn't had time to build.
Can a newly formed LLC buy a property with no rental history yet?
Yes, on a purchase transaction the lender uses market rent from an appraisal, not the LLC's rental history, so a same-week LLC buying its first property qualifies the same as an established one. Investors buying their first deal through a new entity should read how a DSCR loan with no rental history yet is underwritten before assuming they need a track record they don't have.
Do multi-member LLCs face extra requirements when they're brand new?
Multi-member LLCs need a signed operating agreement showing ownership splits and a resolution authorizing the specific member who signs loan documents, regardless of when the LLC formed. The extra step for a new entity is simply making sure that paperwork exists before closing, since a year-old LLC usually already has it filed away.
Get your new LLC pre-qualified
Confirm your entity documents and DSCR ratio before you make an offer.
Verdict: a DSCR loan for a newly formed LLC closes on the same timeline as an established entity in 2026 as long as the five core formation documents are signed before underwriting starts. LoanGuys underwrites DSCR loans for LLC-owned rental properties without an entity-age minimum, which is the standard most non-QM lenders now follow.
FAQ
Can a newly formed LLC get a DSCR loan in 2026?
Yes, a newly formed LLC can get a DSCR loan in 2026 with no minimum seasoning period at most lenders. The LLC needs Articles of Organization, an EIN letter, a signed operating agreement, a borrowing resolution, and personal guarantees from members owning 20% or more.
How old does an LLC need to be for a DSCR loan?
Most DSCR lenders set no minimum age for the LLC — a same-week entity qualifies as long as its formation documents are complete. The property's rental income, not the LLC's age, drives the DSCR ratio the lender underwrites.
Does a new LLC need business credit to qualify for a DSCR loan?
No, a new LLC does not need business credit to qualify for a DSCR loan. The lender relies on the personal guarantee and credit of members owning 20% or more of the entity instead.
What documents does a new LLC need to close a DSCR loan?
A new LLC needs five documents to close a DSCR loan: Articles of Organization, an EIN letter, a signed operating agreement, a resolution to borrow, and government ID for each 20%+ owner. Missing any one of these typically delays closing more than the LLC's age ever would.
Is a personal guarantee required on a DSCR loan for a new LLC?
Yes, a personal guarantee is standard on a DSCR loan for a new LLC, same as for an established one. Every member owning 20% or more of the LLC signs personally, shifting repayment risk away from an entity with no financial track record.
Can you transfer a property into a newly formed LLC after closing a DSCR loan personally?
Some lenders allow a post-closing transfer into an LLC, but this varies by lender and loan terms, so confirm it before closing rather than after. Closing directly in the LLC's name from the start avoids that question entirely.
What DSCR ratio does a new LLC need to qualify?
A new LLC typically needs the same DSCR ratio as any borrower, generally between 1.0 and 1.25 depending on the lender and program. The ratio compares gross rental income to the full mortgage payment, and entity age doesn't change the math.
Do multi-member new LLCs need extra paperwork for a DSCR loan?
Multi-member new LLCs need a signed operating agreement and a resolution naming who can sign for the loan, which is the same requirement established multi-member LLCs face. The only difference is a brand-new LLC has to generate that paperwork before closing rather than pulling it from a file.
One last thing
The detail that trips up most first-time LLC borrowers isn't the entity at all — it's forgetting that every member owning 20% or more has to sign the personal guarantee, not just whoever filed the paperwork. Skip a signature and the file bounces back from underwriting even if the LLC itself is flawless. Set up the operating agreement with signature lines for every qualifying owner before you submit, and the newly formed LLC closes as fast as an established one in 2026.


